


Sold

80 SUMMERBERRY Way
Hamilton, Ontario
3 bed · 3 bath · 1,587 sq ft · Semi-detached
$790,000
Sold · Aug 2026

Eleven years closing the most consequential financial decisions of your life. Over three hundred and fifty million in sales. Five hundred families. One advisor who treats every transaction like the only one that matters, because to you, it is.

Vali Mikho doesn't sell homes. He sells preparation, strategy, and the kind of negotiation that comes from closing more than five hundred transactions across the most competitive corridor in Canadian real estate.


Skip the algorithm. In twenty four hours Vali returns a personalized pricing strategy with comparable sales, recommended timing, and a launch plan tailored to your property. Real human, real numbers, real homework.
Live from the MLS® System and refreshed daily. Every property below is currently available across Hamilton, Burlington, and the surrounding Golden Horseshoe.
Choose a city to see what is currently on the market. Every listing comes live from the MLS® System and refreshes daily.
Westdale, Durand, Kirkendall, Ainslie Wood, the Mountain and the east end.
Old Ancaster, Meadowlands, Heritage Green and the surrounding estate pockets.
Aldershot, Tyandaga, Roseland, Headon Forest and the Lakeshore corridor.
Bronte, Glen Abbey, Old Oakville, West Oak Trails and Joshua Creek.
Lorne Park, Port Credit, Mineola, Erin Mills and Streetsville.
The Ward, Exhibition Park, Kortright Hills and the university district.
Old Milton, Hawthorne Village, Scott, Ford and Bronte Meadows.
High Park, Bloor West Village, Etobicoke and the west end.
Grimsby, Beamsville, Lincoln, St. Catharines and the bench.
Eleven cities, one continuous market, dozens of micro-neighbourhoods Vali knows by name. Tap an area for sold prices, school zones, and recent activity.
Every buyer is different, so the path is too. Choose the situation that matches yours, then open any step to see what happens, how Vali helps, and what to have ready.
We set out what you are trying to achieve, when you want to move, and what the realistic path looks like from where you are today.
Vali maps the whole process in plain language before any paperwork, so you know the order of events and roughly what each stage costs.
A rough moving date, who is buying with you, and any non-negotiables such as school catchment or commute.
You get a mortgage pre-approval and we add the costs that sit on top of the purchase price.
Vali introduces mortgage professionals, then walks through land transfer tax, legal fees, title insurance, inspection and moving costs, and which first-time buyer rebates you may qualify for.
Recent pay stubs, notices of assessment, and a clear picture of your savings and existing debts.
We turn your criteria into a live search and narrow the areas that actually fit your budget and daily life.
Vali sets up MLS alerts and shares what he knows about each pocket: pricing patterns, what tends to sit, and what tends to move quickly.
An honest list of what you need versus what you would like, and your maximum commute.
You start viewing, and each showing teaches you more about what your budget buys in that area.
Vali points out the things that cost money later: age of roof, furnace and windows, grading, layout limitations, and how the home is likely to resell.
A note-taking habit. Photos and a short list of concerns after each showing help far more than memory.
Before writing, we review comparable sales and decide which conditions belong in the offer.
Vali explains what each clause does, what a condition protects you from, and how the deposit and closing date work.
Your lawyer's contact details, and a decision on how quickly you can close.
The offer goes in and the back-and-forth begins, sometimes against other buyers.
Vali handles the negotiation and keeps you anchored to the number you set beforehand, so decisions are made on evidence rather than pressure in the moment.
A firm walk-away number agreed before the offer is presented, not during.
Once an offer is accepted, the conditions are worked through within the agreed deadlines.
Vali coordinates the home inspection, lender appraisal and lawyer review, and explains anything the inspector flags so you can decide whether to proceed, renegotiate or walk.
Availability for the inspection, and prompt responses to your lender's document requests.
Conditions are waived, the file moves to the lawyers, and closing day is scheduled.
Vali keeps the lawyer, lender and other side coordinated, and sends a moving checklist covering utilities, insurance and address changes.
Closing funds at your lawyer, home insurance bound, and movers booked once the deal is firm.
We define what the next home needs to solve that the current one does not.
Vali works through space, location, schools and long-term plans, and is direct about which of those the market can realistically deliver in your range.
A clear list of what is driving the move, and your ideal timing.
We establish what your current property is likely to sell for and what equity that frees up.
Vali prepares an evaluation from recent comparable sales on your street, and outlines what preparation would be worth doing before listing.
Your mortgage balance, any secured lines of credit, and a list of improvements you have made.
Your lender confirms what you can carry, including any overlap between the two transactions.
Vali connects you with mortgage professionals who can explain porting, bridge financing and what qualifying looks like while you still hold the first property.
Current mortgage documents, renewal date, and whether your mortgage is portable.
We weigh the two sequences against your finances and your tolerance for uncertainty.
Vali sets out the real trade-offs of each path in current conditions rather than a blanket rule, since the right answer changes with inventory and with your ability to carry both.
An honest view of how much risk you are comfortable carrying, and whether you have a fallback if timing slips.
Preparation on the current home runs alongside the search for the next one.
Vali coordinates the prep work, photography and launch plan while keeping your search active, so neither side stalls waiting on the other.
Access for trades and photographers, and decisions on decluttering and any recommended repairs.
Offers are negotiated on the sale and the purchase, sometimes at the same time.
Vali negotiates both sides with an eye on how they interact, since a concession on one can create or remove flexibility on the other.
Fast availability to review and respond, as both sides often move quickly.
Conditions and closing dates are aligned as closely as the two agreements allow.
Vali works with both lawyers and lenders to line the dates up. Where a gap remains, he explains the options for bridging or storage early rather than late.
Flexibility on dates where possible, and a plan if the two closings do not land on the same day.
Both deals close and you hand over one property while taking possession of another.
Vali keeps the sequence organised across lawyers, movers and utilities, and stays reachable through the handover.
Movers booked, utilities scheduled at both addresses, and keys and garage remotes gathered for handover.
We establish whether you are buying for monthly income, long-term appreciation, or a mix, and over what horizon.
Vali is direct about what each objective demands in this market, and which property types tend to suit which goal.
Your target hold period, how involved you want to be, and what return would make this worthwhile.
Investment financing is assessed, which differs from financing a home you live in.
Vali introduces lenders experienced with rental properties and explains typical down payment requirements, qualifying treatment of rental income, and why a reserve matters.
Corporate or personal structure decided with your accountant, plus proof of down payment and reserves.
We build a shortlist that fits the strategy rather than whatever happens to be listed.
Vali screens for tenant demand, condition, zoning and the realistic rent for each unit, and rules out properties whose numbers do not hold up.
Your buy box: areas, property types, unit count and maximum price.
Each candidate is modelled on income and expenses rather than list price alone.
Vali works through rent, vacancy allowance, taxes, insurance, maintenance, management and financing costs, and shows the cash flow those inputs produce.
Your financing terms, and any assumptions you want tested.
We rerun the numbers with worse inputs to see what the property does under strain.
Vali models lower rent, higher vacancy and higher borrowing costs, so you can see where the deal stops working before you commit.
A view on how much negative cash flow, if any, you could absorb and for how long.
An offer is prepared with conditions suited to an income property.
Vali structures the offer around the checks that matter here: inspection, review of leases and rent rolls, and confirmation of permitted use.
Your lawyer briefed on the purchase, and availability during the condition period.
The deal closes and the property has to start operating.
Vali coordinates closing, and helps with the handover of existing tenancies or with getting the unit ready and leased where it is vacant.
Decision on self-managing or hiring a manager, plus insurance suited to a rental property.
After a period of operating, actual results are compared against the original model.
Vali reviews where reality differed from the projection and what that means for refinancing, improving the property, or acquiring the next one.
Twelve months of income and expense records for the property.
We clarify whether this is for your own use, for rental, or for resale, and when you actually need it.
Vali explains how pre-construction timelines work, including that occupancy and final closing are separate dates and that delays are common.
Your intended use, and the earliest and latest dates that would work for you.
Projects are compared on more than the renderings and the launch pricing.
Vali reviews builder track records, past delivery timelines, construction quality and location fundamentals, and flags projects he would be cautious about.
Your preferred areas, and whether you want a condominium, townhome or freehold.
The purchase price is only part of what you will pay.
Vali walks through the deposit schedule, development levies and whether they are capped, occupancy fees, assignment fees and closing costs, so the total is clear at the outset.
Confirmation of how much you can put down across the deposit schedule, not just at signing.
Within a project, specific units perform differently.
Vali advises on floor plan, exposure, floor level and layout efficiency, since these affect both livability and how the unit resells or rents.
Your priorities on size, layout, parking and storage.
The agreement is reviewed during the statutory cooling-off period.
Vali flags the clauses that matter, including assignment rights, levy caps and the builder's ability to change dates, and coordinates with your lawyer for the formal review.
A real estate lawyer engaged and available within the cooling-off window.
The project is built over a period of years while you prepare to complete.
Vali passes on builder updates and reminds you of deposit dates, and works with your lender well ahead of closing since approval must be current at that time.
Deposit funds available on schedule, and finances kept stable ahead of final approval.
You inspect the unit before taking occupancy and note deficiencies.
Vali explains the pre-delivery inspection, what to document, and how occupancy fees work in the interim period before final closing.
Time set aside for the inspection, and a careful record of anything incomplete or damaged.
Title transfers, your mortgage funds, and the unit becomes yours.
Vali coordinates final closing with your lender and lawyer, and helps you decide whether to move in, lease it out or sell.
Final closing costs ready, and a decision on how you intend to use the unit.

Preparation and launch dates are set around your property and agreed with you, not fixed to a template. Once the home is live, we watch how the market responds and adjust together. Every timeline below reflects that.
Timing depends on the property, its preparation and current market conditions. Nothing above is a guarantee of a sale within any particular period.
Three hundred fifty pre-construction units. Cash-flow rentals across Hamilton's revitalizing core. Pre-IPO commercial. Vali's investor clients aren't buying homes; they're building portfolios. With math that works.
For investors who want tomorrow's inventory at today's pricing. Curated project shortlists, vetted builder track records, and deposit structures and assignment rights explained before you commit a dollar.
For income-first investors who care about the monthly number. Hamilton-area pockets with a real path to positive cash flow, with rents, taxes, and carrying costs modelled honestly before you offer.
For investors ready to scale past a single door. Duplexes, triplexes, and secondary suites, with guidance on tenant law, financing thresholds, and value-add conversions that lift rents legally.
For long-horizon investors building lasting wealth. Planning across appreciation, leverage, refinancing, and tax efficiency, so each property positions you for the next one.

A worked example showing how commercial numbers are assessed before an offer. This is a teaching illustration only. It is not an available property, not a financing quote, and not a projected return.
Approximately $10,167 per month
Eleven years of transactions across Hamilton, Ancaster, Stoney Creek, Burlington, Brantford, Mount Hope, Welland, and beyond. Below is a selection of recent closings, residential sales, commercial and office space, farmland, and leases alike, each one negotiated, marketed, and closed personally.


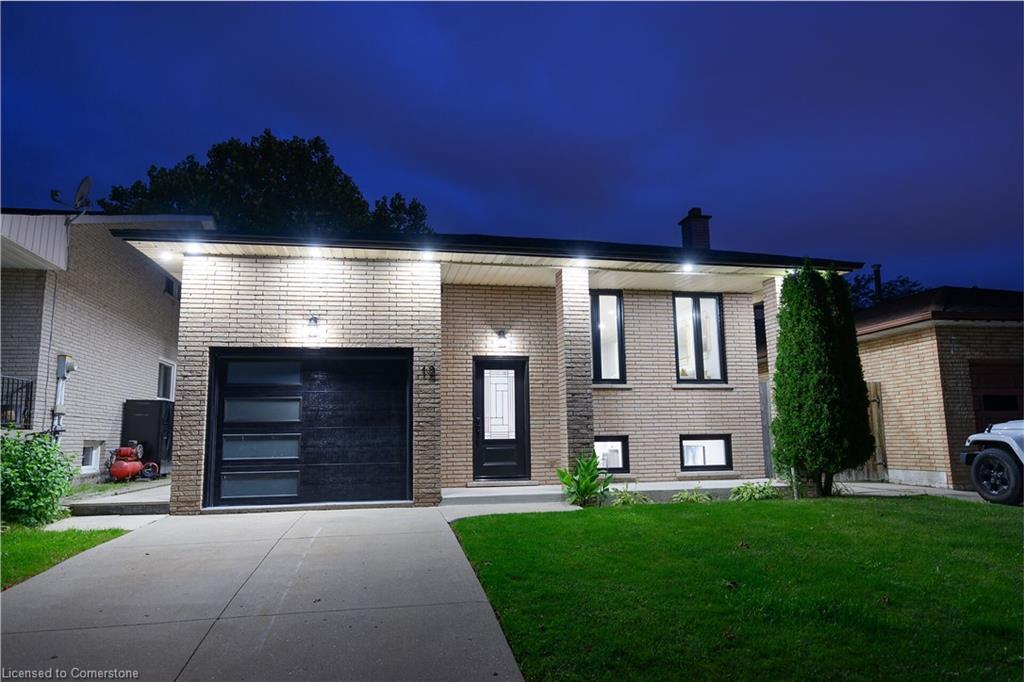
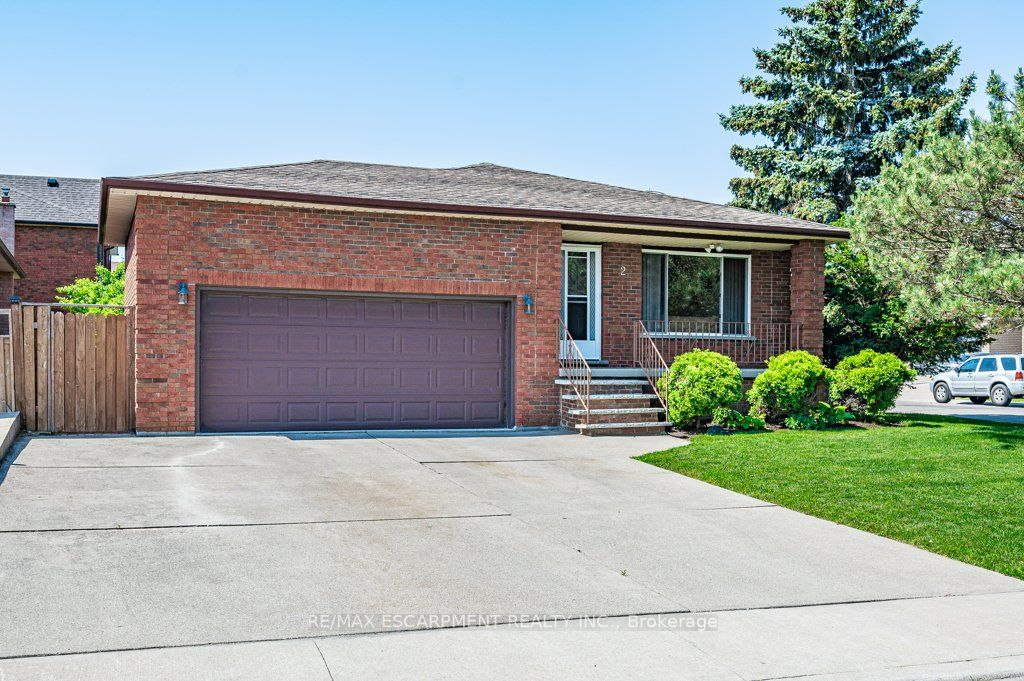
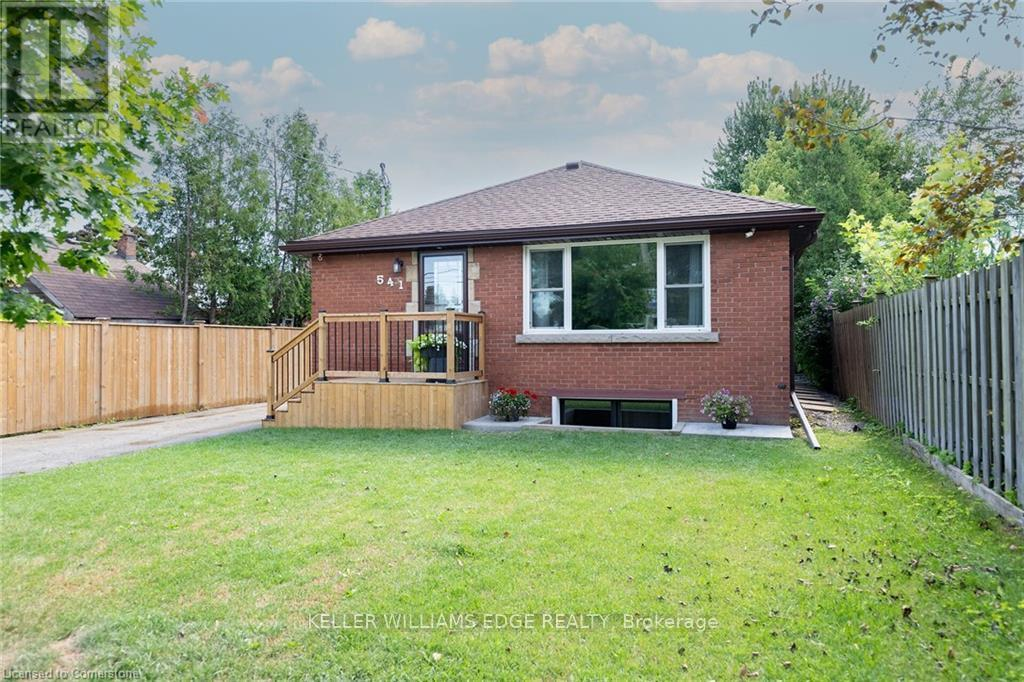
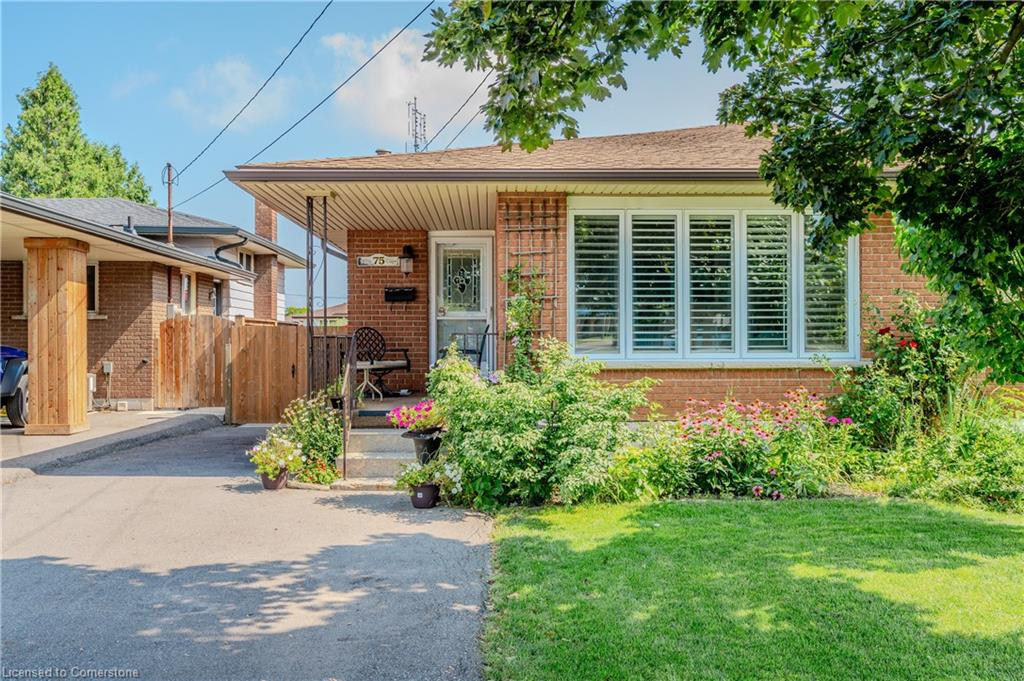
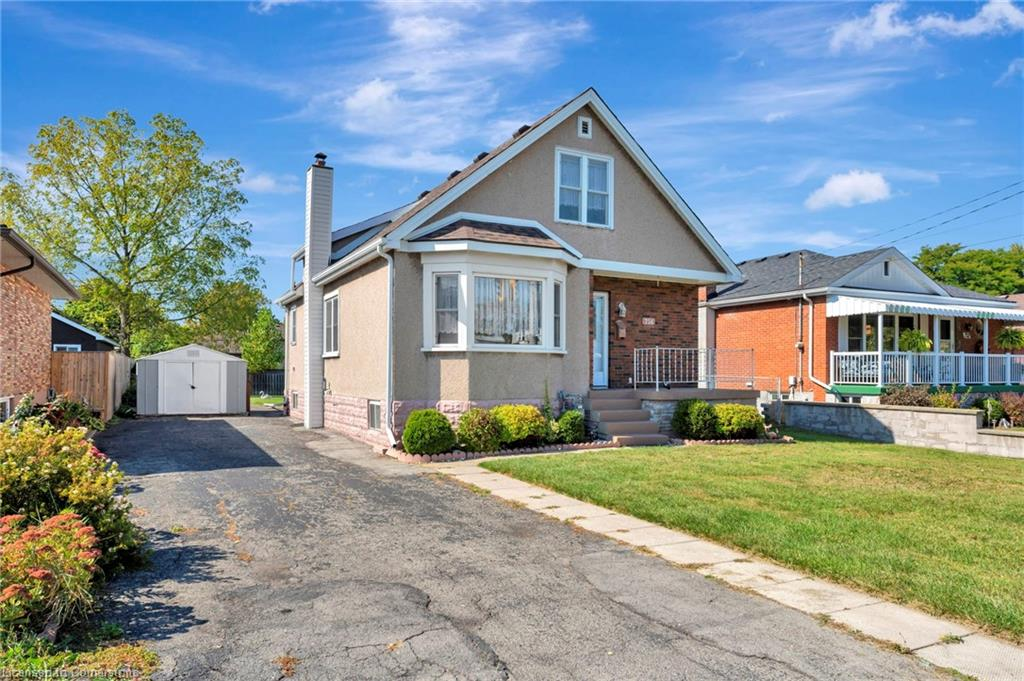
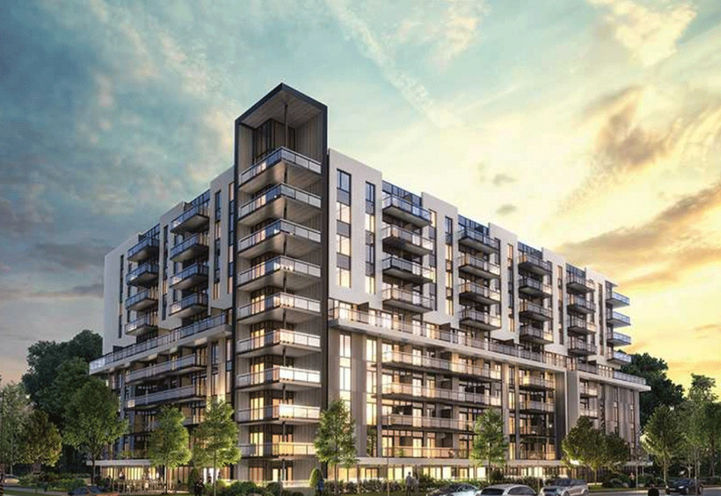
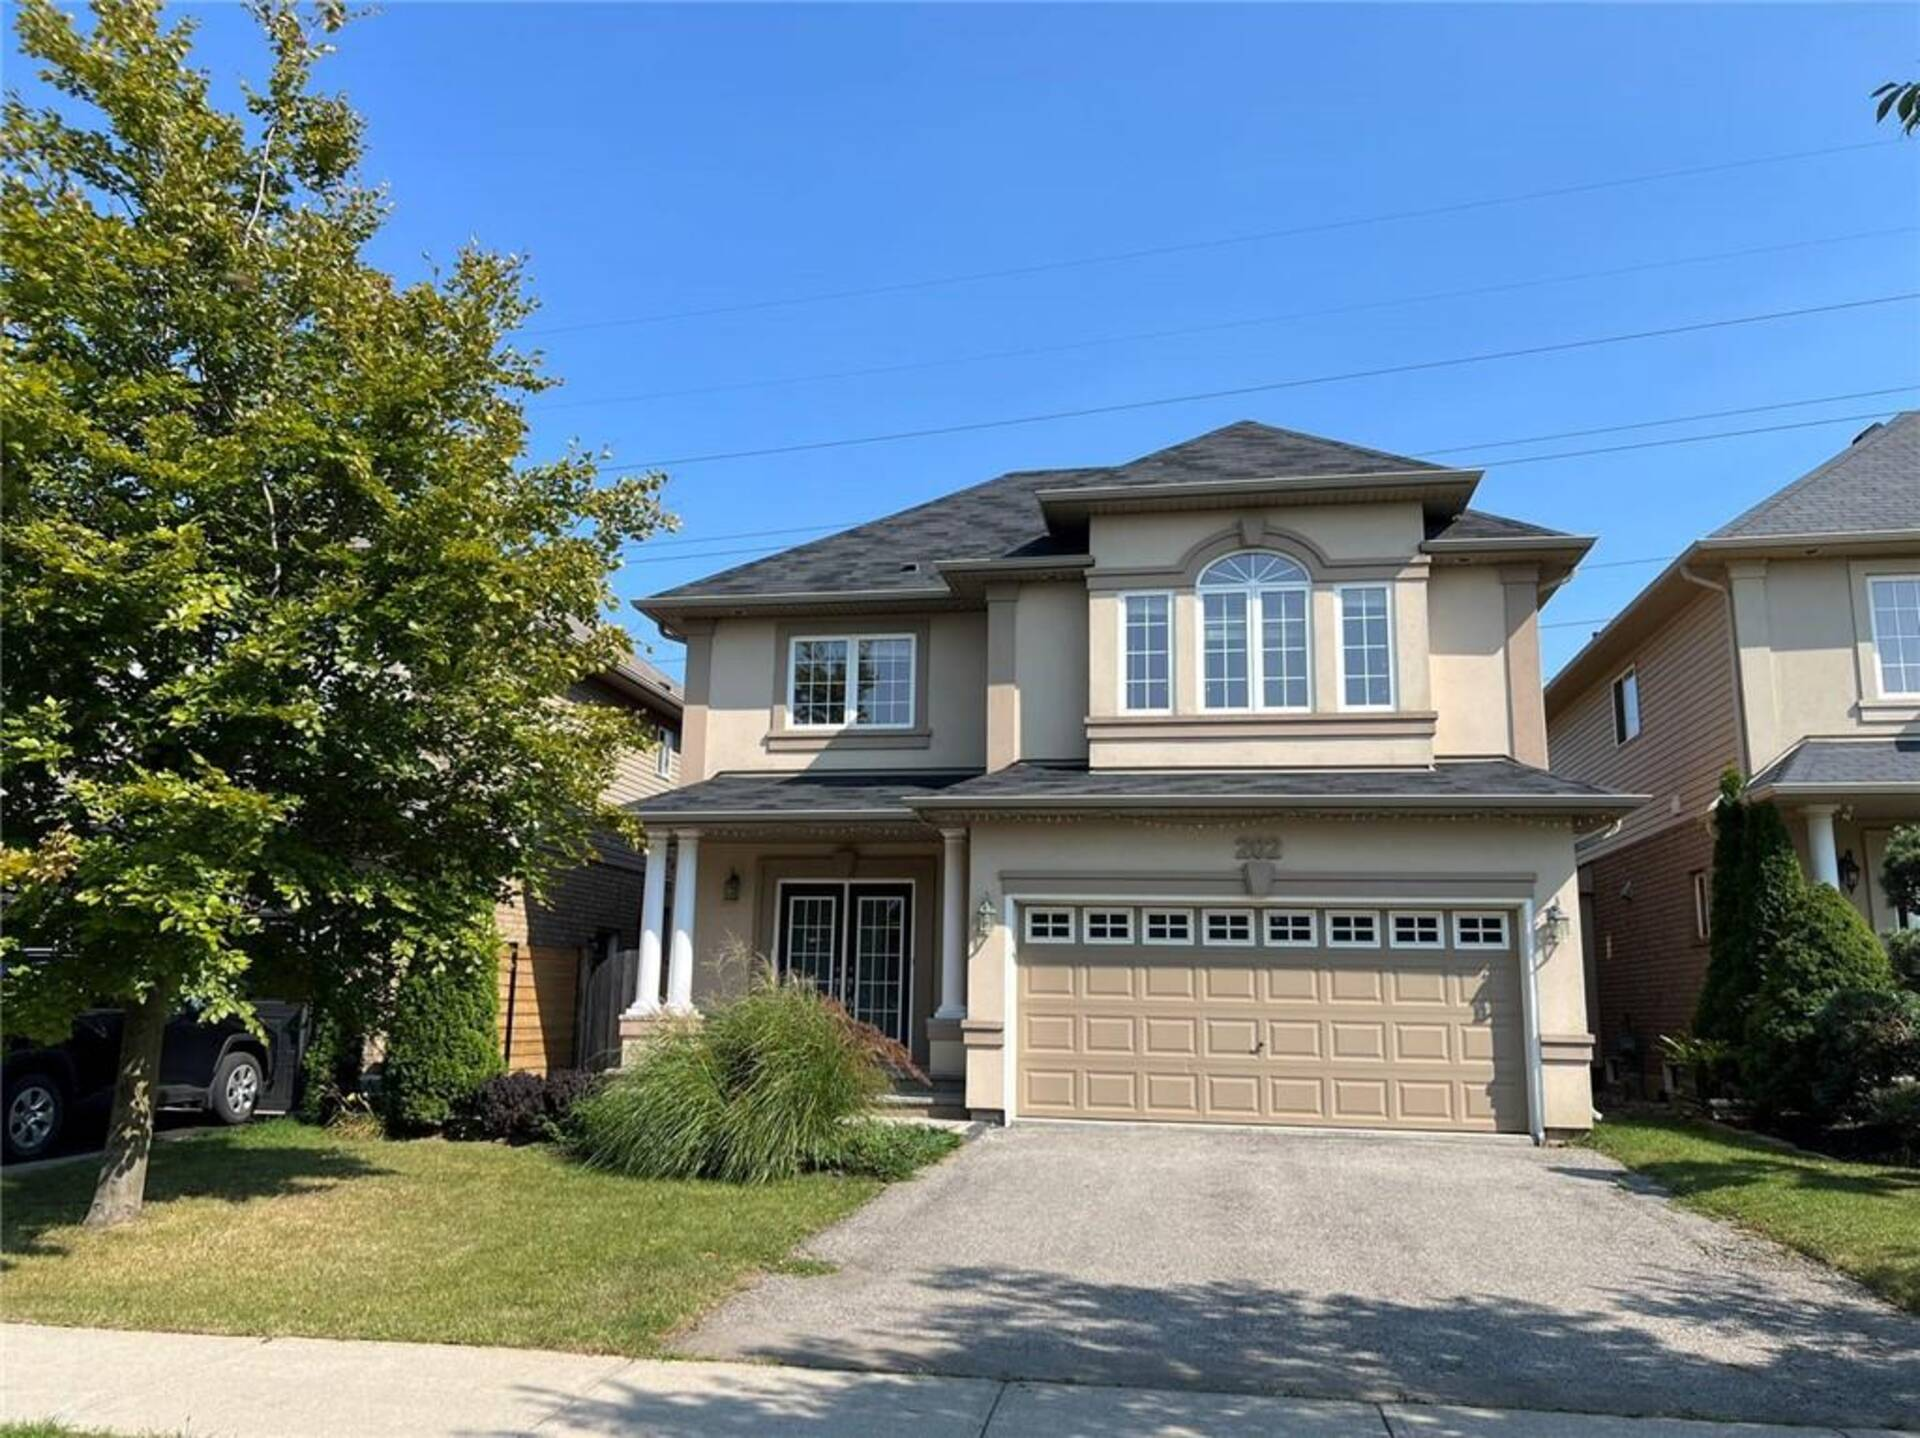
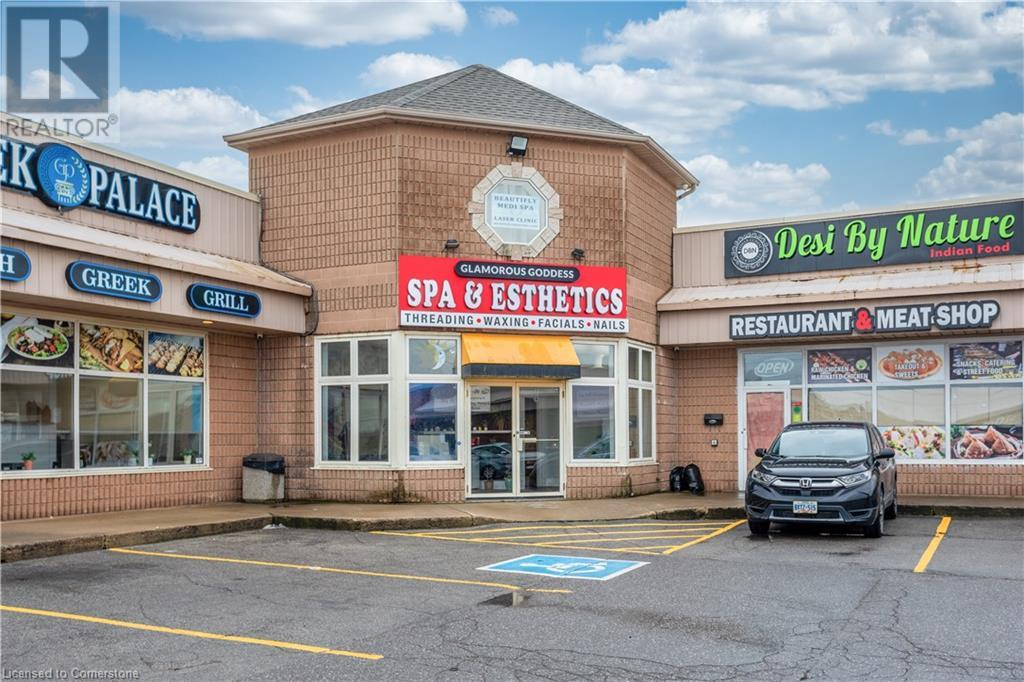
A representative selection of recent transactions. Sale prices shown as reported at closing. Individual results vary by property, timing, and market conditions.
Book Your Free EvaluationThe questions that come up most often from buyers and sellers across Hamilton and Burlington. If yours is not here, call or send a note. Straight answers, no obligation.
Values vary widely by neighbourhood, lot size, condition, and what has actually sold on your street in the last ninety days. Online estimators miss renovations, exposure, and the demand in your specific pocket, which is where most of the difference lives. A free in-person evaluation reviews recent solds within a few blocks, the inventory you would be competing against, and the pricing strategy most likely to produce competing offers rather than a slow drift downward.
Days on market depends on price band, season, and preparation. Well-prepared homes priced to the market often sell within one to three weeks. Homes priced above market or listed without preparation can sit considerably longer, and every week of sitting costs leverage. Pre-market preparation, professional photography, and a launch that concentrates showings into the first weekend have the single largest effect on both speed and final price.
Budget roughly 1.5 to 4 percent of the purchase price. The main items are land transfer tax, legal fees and disbursements, title insurance, a home inspection, and adjustments for prepaid property taxes or utilities. First-time buyers may qualify for a land transfer tax rebate. Exact figures depend on the property and your lawyer, so confirm the specifics with your legal and mortgage professionals before you firm up.
You are not required to have one, but the sales centre staff work for the builder, not for you. Representation gets you platinum or early access allocations, a review of the agreement during the cooling-off period alongside your lawyer, attention to development levy caps and assignment terms that are easy to miss, and a realistic model of carrying costs at occupancy. Vali has sold over 350 pre-construction units since 2015.
The deposit submitted with an offer is separate from your down payment. It typically ranges from a few thousand dollars up to about five percent of the purchase price, depending on the local market and how competitive the offer needs to look. Separately, the minimum down payment in Canada is five percent on the first five hundred thousand dollars and ten percent on the portion above that, with twenty percent required to avoid mortgage default insurance.
Primary focus is Hamilton and Burlington, where the majority of transactions happen. Active coverage extends through Ancaster, Dundas, Stoney Creek, Grimsby, Waterdown, Oakville, Milton, Mississauga, and Toronto. If you are buying or selling anywhere along the western Golden Horseshoe or into the GTA, it is covered.
In most residential resale transactions in Ontario, the listing brokerage offers compensation to the co-operating brokerage out of the seller's proceeds, so buyers typically do not pay directly. Arrangements vary by transaction and are set out in a written buyer representation agreement before you start looking, so there are no surprises. Any exceptions are explained up front.

Vali Mikho began his real estate career in 2015 with a simple conviction: the properties people sell and buy are not transactions to him, they are inflection points in their lives. Since then, he has closed more than three hundred and fifty million dollars in residential, commercial, and pre-construction sales across the Hamilton, Burlington, and GTA corridor. That standard holds whether the file is a first home, an income property, or a commercial lease.
He works with his clients the way a private banker works with theirs. Slowly when it should be slow. Decisively when it has to be. Always with the math, always with the homework, always in their corner.
Vali Mikho
Realtor · HomeLife Professionals Realty Brokerage · Burlington
Whether you're three months away from listing or three years away from your first home, the smartest first step is a conversation. No pressure, no commitment. Just clarity.
